Synthetic example
Synthetic example: Owner report
Synthetic example. The same software produced this report from invented documents for an invented condominium, for the year 2099. Every figure, name and number in it is invented. It describes no real building, unit or person.
Download this synthetic example as a PDF Start an Owner check
Synthetic example
FRC / FEE & RESERVE CHECKOWNER REPORT
What this means for you as an owner.
Synthetic Condominium Corporation No. 9999 / Suite 201 / 2099 fiscal year
Budget and study: 2099 / Work schedule read: 2099 only / Audited to December 31, 2098
THE SHORT ANSWER
Your maintenance fee matches the fee schedule. The 2099 budget puts $103,020 less into the reserve than the corporation's study recommends.
Does your maintenance fee match the documents?
Matches the fee schedule
You pay $810.76 a month, including a $19.61 temporary charge. That matches the 2099 fee schedule. (S3 p. 1; S5 p. 1)
$810.76
Your maintenance fee
With $19.61 temporary
$896.61
With the study's contribution
$85.85 more than you pay; not an approved fee
What do the documents show about the board's planning?
Yearly contribution below the study
The 2099 budget puts $200,000 into the reserve; the study recommends $303,020 ($103,020 more).
No newer adopted plan or explanation for the difference was found. (S1 p. 1; S2 p. 1)
What deserves your attention?
Condition not assessed
No engineering or condition report was supplied, so the building's current condition cannot be assessed from these documents.
The study schedules $2,810,000 of work for 2099 only (2100 to 2103 not read), including $40,000 of contingency; a date alone is not evidence of failure.
2099 reserve contribution $103,020 below the study
Your share is $85.85 a month. How it is closed is not stated. (S1 p. 1; S2 p. 1)
Garage roof slab waterproofing: $950,000 in 2099
The largest work planned soonest. Ask if it is contracted, delayed or done. (S2 p. 3)
Levied assessments not checked
The budget package says none is proposed; that does not cover any already levied. (S1 p. 2)
The $19.61 temporary charge
Ask when the deficit recovery charge ends and what it recovers. (S3 p. 1)
Synthetic example
Why this matters and what to ask next.
The nearest work, the reserve funding, and three questions for management.
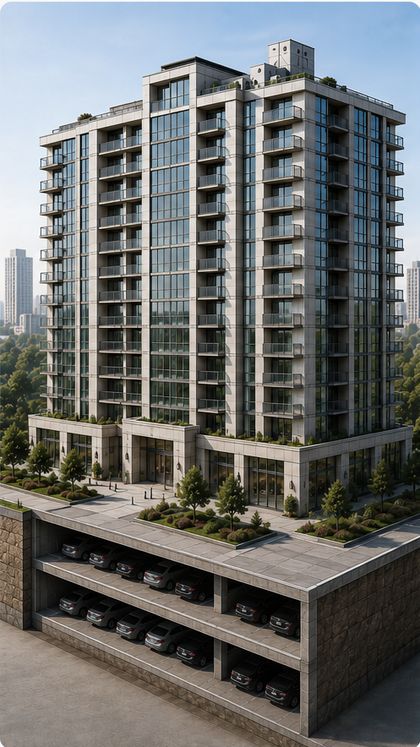
Nearest significant work
Garage roof slab waterproofing
2099 / $950,000 S2 p. 3
Main Roofing System
2099 / $700,000 S2 p. 3
Window Replacement - Phase 1
2099 / $520,000 S2 p. 3
Plus $40,000 contingency in 2099: money set aside, not a building part.
The schedule read covers 2099 only (2100 to 2103 not read).
Reserve funding this year
Budget$200,000
Study$303,020
$103,020 a year less than the study. Your 1.0% share: $85.85 a month.
Sources: S1 p. 1; S2 p. 1
Reserve outlook
The study's projection stays above zero; lowest $58,020 (end of 2099).
This chart assumes the reserve contributions in the study. The 2099 budget contributes $103,020 less.
| Year | Balance |
|---|---|
| 2098 | $152,000 |
| 2099 | $58,020 |
Source: S2 p. 5. The study's figures, not a forecast by this report.
Three questions for management
Has the board adopted a funding plan that replaces the study's $303,020 reserve contribution for 2099, or does it plan to close the $103,020 gap?
When does the $19.61 deficit recovery charge end, and what shortfall does it recover?
Is the garage roof slab waterproofing work ($950,000, 2099) contracted, delayed or done?
Synthetic example
The building in detail.
Planned replacements are not evidence that something has failed.
Location 1: Underground garage
2099 / $1,130,000
The parking levels below ground. "Roof slab waterproofing" is the waterproof layer on the concrete slab that forms the garage's roof (the study lists it under "Underground Parking Garage"). Study items: Roof Slab Waterproofing System; Parking Garage Painting.
Location 2: Windows, balconies and walls
2099 / $780,000
The outside walls, windows and balconies. Study items: Window Replacement - Phase 1; Balcony Concrete Repairs.
Location 3: Roof
2099 / $700,000
The roof covering that keeps water out of the building. Study items: Main Roofing System.
Location 4: Fan-coil units
2099 / $160,000
The heating and cooling units inside the suites. Study items: Fan Coil Unit Replacement.
Source: Reserve Fund Study, p. 3. Every item behind these amounts is in the full list at the end.
What the documents do not tell us
These are the study's estimates for 2099 only (2100 to 2103 not read), not contractor quotes. The documents do not confirm that the scheduled work was contracted or completed. No engineering or building-condition report was supplied, so the condition of these parts is not described. No work was found for: Elevators. That does not mean none is needed. The study also sets aside $40,000 of contingency, a financial allowance shown on no part of the building.
Synthetic example
Follow the money.
The yearly contribution and the reserve balance answer different questions.
Your monthly payment in parts
Now: $810.76
Running the building $624.48 + Reserve fund $166.67 + Temporary charge $19.61 = $810.76
With the study's reserve contribution: $896.61
Running the building $624.48 + Reserve fund $252.52 + Temporary charge $19.61 = $896.61
- Running the building
- Reserve fund
- Temporary charge
Basis of the split: the budget puts its reserve contribution out of the owners' $949,380 ("Maintenance Fees 949,380", S1 p. 1), 21.1% to the reserve; the fee schedule's yearly total repeats that figure. "TOTAL REVENUE $972,912" is total revenue, which also counts other lines, so it is not used. Your payment is assumed to divide like the whole budget.
The $19.61 temporary charge is a deficit recovery on your fee schedule (S3 p. 1), shown in amber. It is in both amounts only while it applies.
1. How much goes into the reserve each year?
The 2099 budget$200,000
The Reserve Fund Study, for 2099$303,020
Source: Budget Package, p. 1; Reserve Fund Study, p. 1.
$103,020 a year less than the study
Your 1.0% share: $85.85 a month
The reserve contribution is what the corporation puts into the reserve fund each year. The balance is what the fund holds at a point in time.
2. How could the reserve balance change?
The Reserve Fund Study's own projection of the year-end balance, 2098 to 2099.
This chart assumes the reserve contributions in the study. The 2099 budget contributes $103,020 less.
| Year | Balance |
|---|---|
| 2098 | $152,000 |
| 2099 | $58,020 |
Starting point: $152,000 at the end of 2098, as the study projects it.
Contributions, spending, interest and inflation are the study's own assumptions. This report does not change or extend them.
This is the study's projection, not a forecast by this report or a decision by the board. Positive balances alone do not establish long-term adequacy.
Source: Reserve Fund Study, p. 5.
$152,000
Reserve fund balance on December 31, 2098, from the audited statements
Up from $100,000 at the start of that year. A past balance. It does not show what the fund holds today or whether it is enough.
Source: Audited Financial Statements, p. 1.
Synthetic example
The next five years in detail.
Estimated project spending for the whole corporation, not a charge to your unit.
$2.81 million
Listed estimates for 2099 only (2100 to 2103 not read), exactly $2,810,000, of which $40,000 is contingency. Years the schedule does not reach are not established, not $0.
- $2.81 million
2099
Garage and 3 more
- Not established
2100
Not covered by the schedule read
- Not established
2101
Not covered by the schedule read
- Not established
2102
Not covered by the schedule read
- Not established
2103
Not covered by the schedule read
These are estimates for the whole corporation, paid over time from the reserve fund. They are not charges to your unit, and a project price alone does not show whether an extra payment will be needed.
The schedule also lists 11 items for 2096 to 2098, before 2099; whether that work was done is not stated. See the full list at the end.
Synthetic example
The evidence behind the numbers.
The documents, what was read from them, and how each amount was worked out. You do not need to read this section to understand the main result.
Documents read
- S1
Budget Package 2 pages; used: pp. 1, 2
2099 reserve contribution $200,000; the budget line the fee split is based on; a disagreement or ambiguity discussed in this report; statement on special assessments. Text read.
- S2
Reserve Fund Study 5 pages; used: pp. 1, 3, 5
2099 reserve contribution $303,020; schedule of major work: 18 items, 2096 to 2099; year-by-year balance projection. Text read.
- S3
Unit Fee Schedule 1 page; used: p. 1
Monthly payment $810.76, including $19.61 deficit recovery. Text read.
- S4
Audited Financial Statements 1 page; used: p. 1
Reserve balance $152,000 on December 31, 2098. Text read.
- S5
Declaration 1 page; used: p. 1
This unit's share 1.0%. Text read.
Text read means the software read the words on the pages. Read by text recognition means the pages were scanned images and the software recognized the words on them. Neither guarantees that every table in a document was read.
Check the calculation
Reserve difference: $303,020 - $200,000 = $103,020 a year.
Current payment: $791.15 + $19.61 temporary charge = $810.76.
Your share of the reserve difference: $103,020 x 1% / 12 = $85.85 a month.
With the study's contribution: $810.76 + $85.85 = $896.61 a month (a scenario, not an approved fee).
Scenario against your fee: $896.61 - $810.76 = $85.85, which is 10.6% of your current payment.
Assumptions
- The operating budget and other income are taken exactly as the corporation adopted them; only the reserve contribution is replaced by the study’s.
- This split assumes every owner’s fee is divided between operations and the reserve fund in the same proportion as the budget as a whole.
- Suite 201 is Level 2, Unit 1 in the Declaration. You confirmed this reading of your suite number; no document you uploaded states it.
- Amounts are in Canadian dollars, as the documents state them. No interest, inflation or later decision is added.
Where the documents disagree or are unclear
- Owners' yearly fees and total revenue are different figures, not a conflict: "Maintenance Fees 949,380" is what owners are charged; "TOTAL REVENUE $972,912" also counts other revenue lines ($23,532 more). This report uses the owners' line (Budget Package, p. 1).
What was not established
- No engineering or building-condition report was uploaded, so this report does not describe the building’s current condition. The Reserve Fund Study was used for its plan and costs; any condition notes it contains were not assessed, and it is not a physical inspection.
- Work after 2099: the schedule that was read lists nothing later, which does not show that none is planned.
How to use this report
What this report uses
- Software made this report from the documents you supplied. No person has checked it.
- It uses only those documents. A risk that is not mentioned may still exist.
- When documents differ, the report says so. If the documents show which figure applies, the report uses it and says why. If not, it does not choose.
- A figure the documents do not establish is shown as not established.
What it does not do
- It is not legal advice or legal representation. It is not an audit, an engineering opinion, a reserve fund study, or accounting or tax advice.
- It is not a building inspection or emergency help. It does not judge the building's condition or safety.
- If this report shows no safety warning, that does not mean the building is safe.
- It does not predict board decisions, special assessments or fee increases.
- It does not check whether the operating budget is enough to run the building.
Access and help
Questions about this report: help@condoowneradvocate.ca. Support does not interpret the result or give advice.
Appendix: all scheduled work
For reference. Every item read from the Reserve Fund Study. You do not need to read this appendix to understand the report.
18 items from the Reserve Fund Study, in the years it plans them. Estimates for the whole corporation.
| Year | Item | Estimate | Page |
|---|---|---|---|
| 2096 | Main Roofing System | $655,317 | p. 3 |
| 2096 | Contingency | $40,000 | p. 3 |
| 2097 | Roof Slab Waterproofing System | $900,000 | p. 3 |
| 2097 | Balcony Concrete Repairs | $220,000 | p. 3 |
| 2097 | Parking Garage Painting | $180,000 | p. 3 |
| 2097 | Fan Coil Unit Replacement | $150,000 | p. 3 |
| 2097 | Contingency | $40,000 | p. 3 |
| 2098 | Window Replacement - Phase 1 | $500,000 | p. 3 |
| 2098 | Parking Garage Painting | $190,000 | p. 3 |
| 2098 | Contingency | $40,000 | p. 3 |
| 2098 | Roof Slab Waterproofing System | $30,000 | p. 3 |
| 2099 | Roof Slab Waterproofing System | $950,000 | p. 3 |
| 2099 | Main Roofing System | $700,000 | p. 3 |
| 2099 | Window Replacement - Phase 1 | $520,000 | p. 3 |
| 2099 | Balcony Concrete Repairs | $260,000 | p. 3 |
| 2099 | Parking Garage Painting | $180,000 | p. 3 |
| 2099 | Fan Coil Unit Replacement | $160,000 | p. 3 |
| 2099 | Contingency | $40,000 | p. 3 |